From AI agents to autonomous operations
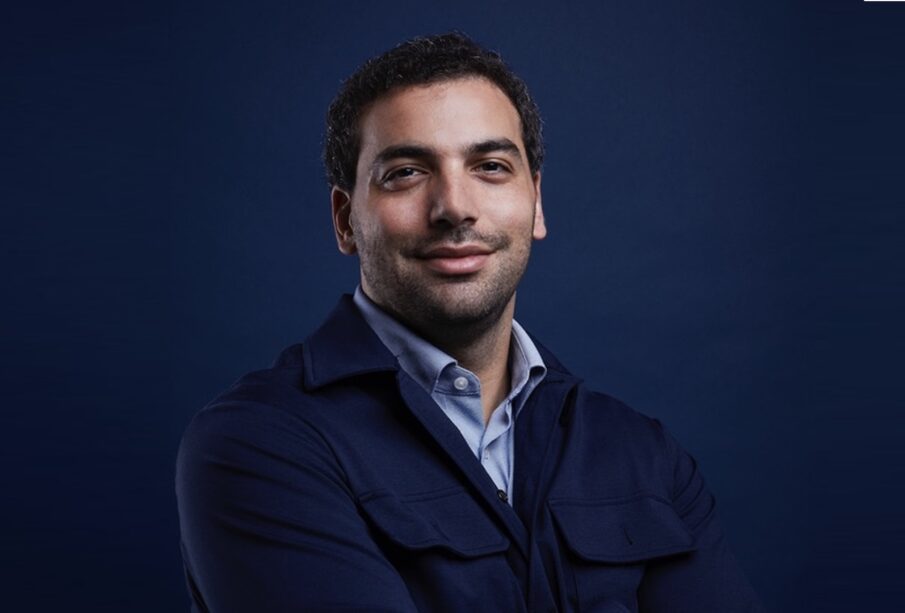
Karim Daoui, Co-Founder & CRO at Beam AI
Karim Daoui, Co-Founder & CRO at Beam AI, discusses the shift from AI experimentation to enterprise-scale Agentic Process Automation, the growing demand for measurable business outcomes, and how self-learning agents, process discovery and governance are shaping the next phase of enterprise AI adoption.
Beam AI is positioning itself as an Agentic Process Automation platform, so how has the company evolved over the past couple of years and what have been the major milestones in that journey?
Beam started in Berlin in 2022, before ChatGPT launched, with an idea that sounded strange at the time: software should evolve itself instead of being rebuilt every quarter.
In the early days we focused on self-evolving intelligence systems, because fixed automation breaks the moment the business changes, and business now changes weekly.
From there we moved from scripted workflows to autonomous agents that handle end-to-end work in finance and HR, built in natural language instead of code.
The next step was getting agents to hold up in production. Most agents work in a demo and fail on real data, so we built self-learning and a task-level evaluation framework that lets accuracy improve over time. That took us from pilots into production with Volkswagen Group, Hitachi, MHP in the Porsche Group and Americana.
This year we added mapping before building. Enterprises kept asking us which processes were worth automating in the first place, and that became our Process Discovery work and the Operating Diagnostic that starts it: a structured map of how an organisation actually runs, with governed agents as the execution layer on top.
Along the way Beam grew from a Berlin team to roughly 40 people across Berlin, New York, Dubai, Abu Dhabi, Karachi and Sydney, with a partner network that includes IBM, Cisco, AWS, NetApp, Sopra Steria, Roboyo, CNTXT, Alloyed and, here in the UAE, Innoventures. Beam is registered in the Abu Dhabi Global Market and operates from Hub71, and we have a team onsite in the UAE.
As enterprises move beyond AI experimentation towards production deployments, where are you seeing the strongest demand for Beam AI today in terms of industries, business functions and use cases?
What we see is a consistent pattern: high-volume work that depends on judgement sitting in somebody’s head instead of in a system.
By function, the strongest demand is in finance operations: accounts payable and invoice handling, order-to-cash, collections and reconciliation. Then HR and recruiting: screening, scheduling and onboarding.
Then shared services and back office, and increasingly supply chain and procurement.
By industry, four clusters are moving fastest: staffing and RPO, business process outsourcing and shared services, banking and insurance, and manufacturing, retail and hospitality operations.
What has genuinely changed in the last year is the question I get asked in meetings. In 2024 it was “can you build an agent for this”, and now it is “which process, at what accuracy, and what does it save”. Buyers have seen the gap between generative AI spend and generative AI results. They have stopped buying capability and started buying outcomes.
Three deployments show the shape of it. A German automotive supplier automated 96 percent of inbound order updates at 95 percent accuracy, with 23 percent fewer manual errors. A European neo-bank took address-verification accuracy inside its KYC process from 60.6 percent to 95.7 percent through self-tuning, with no prompt engineering. A debt collection operator runs over 100,000 cases a month through our agents, which now handle the first and second touchpoint with every debtor before a human is involved.
What are your major customer segments globally and in the Middle East, and where are you seeing the strongest traction?
Globally Beam serves three segments. The first is large enterprise operations in manufacturing, automotive, insurance and banking, where we work with MHP in the Porsche Group, among others.
The second is outsourcers, where automation is the product: RPO, staffing and BPO firms such as Booth & Partners, for whom margin is a direct function of how much work runs without a person touching it.
And the third is consumer and hospitality operations running very high transaction volumes, such as Americana and Limehome. In the Middle East, which is the market I work in, the strongest traction is in the back office of large cross-departmental groups. Americana is in production, and the programme runs out of the UAE. The pull here is finance and shared services first, HR second.
The other line of work I would point to is public sector. Under its National AI Strategy 2031, the UAE has set one of the most ambitious public-sector AI agendas globally, and with our local partner we have been building a custom version of the platform for exactly that bar: Arabic as a first-class language rather than a translation layer, alignment with UAE information assurance standards, in-country deployment, and a full audit trail on every agent action.
The GCC moves particularly fast, and I say this having sat in the equivalent meetings elsewhere. Boards here have an AI mandate with budget attached rather than a curiosity project.
How quickly are customers moving from initial deployments towards broader enterprise adoption?
Faster than the industry average, and I will be specific about why.
Delivery runs in four phases: explore in weeks one to four, prove in weeks five to twelve, scale from month four to month nine, and continuous optimisation from there. So a customer typically has a production agent inside a quarter and a scaled programme inside a year.
At the fast end, Americana had its first agent live in under 30 days, automating 80 to 90 percent of the report restructuring behind its CFO reporting and saving over 700 hours a year. At the scaled end, Booth & Partners screened 88,299 CVs through our agents at a 97.8 percent completion rate, with over 6,500 hours of recruiter work automated. Screening went from six or seven minutes per candidate to under two minutes, and time-to-hire came down by around 75 percent, from as much as two months before.
The second process is always cheaper than the first. By then the integrations, the governance model and the evaluation harness already exist.
With established automation vendors and a growing number of AI agent platforms competing for enterprise workloads, where do you see Beam AI’s key differentiation in the emerging Agentic Process Automation market?
Three things, and the first is the hardest to copy.
We map before we build. Before deploying anything, we map how the operation actually runs, score every process on return against complexity, and specify the ones worth doing. Enterprises do not fail at buildingagents, they fail at choosing which agent to build, and then discover eight months later that they automatedsomething that did not matter.
Our agents get more accurate over time, not less. Traditional automation degrades as reality drifts away from the rules it was written against. Our agents treat every human correction as a training signal, with a task-level evaluation framework behind it.
We also stay neutral on infrastructure and on models. Our agents run in the cloud or on-premises, including on Cisco hardware, and they work with whichever model fits the job.
With rising concerns around Agentic AI autonomy, how do you balance greater autonomy with the reliability, governance and human oversight enterprises require for business-critical processes?
We treat autonomy as something an agent earns process by process, not something you switch on across a platform.
Every deployment starts in shadow mode. The agent runs alongside the live process without touching it, and its output is compared against what the team actually did. Nothing reaches production until that evidence exists.
We measure at the level of individual tasks rather than the system as a whole. Saying an agent is 90 percent accurate tells you very little on its own, so we measure each step and know exactly which one fails and why.
Agents act through declared actions with defined permissions rather than open-ended prompts, and consequential steps route to a human for approval. Every action carries an audit trail, which we treat as part of the product. That is a big part of why the platform holds up in banking and other heavily regulated industries.
We also show confidence openly. Where we are not certain, we say so on the page, because overclaiming certainty is how trust gets destroyed in this category.
Underneath all of that sit the enterprise controls: SOC 2 certified, GDPR-compliant and HIPAA-ready, with on-premises deployment where residency demands it.
The real risk in this market is agents that nobody can measure. An agent running at 70 percent accuracy while reporting itself as working is far more dangerous than an autonomous one you can audit line by line.
The standard here goes beyond whether it worked: you need to be able to prove what it did, why it did it, and who was watching. That is a high bar, and it is the right one.
Tell us about some of your key technology and ecosystem partnerships and how important they will be as you scale the business.
Partnerships are not a side channel for us. They are how enterprise AI actually gets bought, because it is bought through infrastructure and implementation teams the customer already trusts.
Cisco is the most significant for this region. Beam was approved as a Cisco Developer in April and is listed in Cisco’s AI ISV showcase, a joint go-to-market partnership rather than a reseller arrangement, and we work with Cisco’s team on enterprise accounts in the Gulf. Our agents deploy on Cisco UCS and Unified Edge hardware, which means a Middle East enterprise can run autonomous agents entirely on infrastructure it already owns and already trusts. That is a conversation I have almost weekly. Innoventures is our local partner here in the UAE, and that partnership is about meeting a specific standard rather than adding reach.
IBM, AWS and NetApp give us reach into enterprise accounts, cloud estates and data infrastructure at a scale we could not build alone.
System integrators including Sopra Steria and Roboyo carry delivery capacity into markets where we do not have local teams, and regional partners such as CNTXT extend that into the GCC specifically.
Then there are managed services partners, most recently Alloyed in the United States, announced in September, where the model is deliberately hybrid: our agents handle the standard path and their operators handle the exceptions. Not every enterprise wants to run agents itself, and we would rather meet that honestly than pretend the platform alone is the whole answer.
For a company of our size, partners are the difference between selling in five markets and selling in thirty.
Looking ahead over the next two to three years, how do you expect the market for AI agents and Agentic Process Automation to evolve, and where do you want Beam AI to be positioned as enterprises become increasingly AI-native?
Three predictions, and I am fairly confident about the first.
Agent sprawl, then consolidation. Within two years the average large enterprise will have multiple agents from multiple vendors, and no single view of what they touch, what they cost, or where they overlap. That becomes a governance problem before it becomes a technology problem. The layer that resolves it is the layer that wins.
Procurement changes shape, with buying shifting from seats and licences to processes and outcomes. We will not be asked how many agents we sold, we will be asked which processes we own and at what measured accuracy, and accuracy becomes a contractual term rather than a slide.
And the operating model becomes the asset. Enterprises will discover that the constraint was never the models, it was that nobody had an accurate, current map of how the organisation actually runs. You cannot make an operation AI-native when its real process knowledge lives in the heads of dozens of people
Beam wants to be the self-evolving operating model for enterprise AI: the living map of how the enterprise works, with governed agents running through it.
Put plainly: we would rather own the layer that decides what gets automated and proves it worked than compete on who can ship the most agents.
What were the key highlights of your participation at AI Everything Abu Dhabi, and how did the event support your engagement with the regional market?
Our regional team was at ADNEC on 6 and 7 October.
We participated because this region has moved past the pilot conversation faster than most markets Beam operates in. The people attending AI Everything are not asking whether to deploy AI. They come with budgets, board mandates and lists of processes. That is a much better conversation than the one happening at most AI events, and it is why we invest so much time here.
We showcased two things at our stand.
The first was a live Operating Diagnostic, the first step in mapping an operation. Visitors could bring us a real process, and we would map it with them on the spot, rank it on value against effort, and give them a view of their own operation rather than a brochure about ours. This was one of the key areas we wanted visitors to explore.
The second was our agents in action, running live on the stand through real finance and HR tasks, reading inputs, making decisions and flagging what they were not sure about. We also presented walkthrough videos of the different agents so visitors could see how each one works through its process from start to finish.
Alongside that, we highlighted the sovereign-ready work we are doing with our partners, including Arabic-first agents, in-country deployment and full auditability.
Our message to visitors was simple: bring us your hardest process, the one that still runs on a spreadsheet and one person’s memory. Those are the conversations worth having.

Leave a reply